
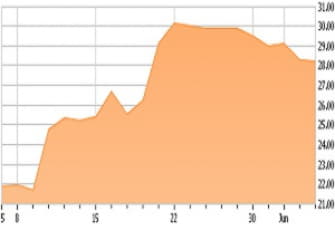
Shares of Lumber Liquidators (NYSE:LL) are up about 101% over the past twelve months, and, in my opinion, current shareholders should count themselves lucky and move on to find greener pastures elsewhere. Those who are considering buying shares at these levels should avoid them. I'll outline my reasoning below by reviewing the financial history here, along with providing a model for the future of the company based on the retained earnings growth.
Three Troubling Things About Lumber Liquidator's Financial History
When reviewing Lumber Liquidators' financial history, there are many things that jump off the page, none of them good. For instance, the level of long-term debt has ballooned in a very short time (from zero in 2014 to ~$72 million today). Additionally, 99% of this debt is due within 3-5 years, suggesting some risk to the capital structure in a few years. If the company isn't able to refinance at favourable rates, the business could be imperiled.
READ FULL ARTICLE HERE

