
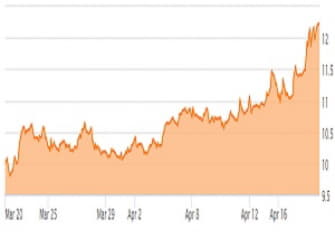
I have made some noise recently concerning what I believe to be excessive management compensation at Lumber Liquidators (LL). The fundamental argument is that while shareholders have seen the value of their investment drop over the years, management continues to receive very healthy paychecks and increasing equity compensation. It all seems a little unfair.
In response, I have formed an ad-hoc group (Lumber Liquidators Value Committee) composed of several large holders of Lumber Liquidators shares (myself included), and we are actively soliciting large and small shareholders to vote against management's proxy proposals to be tabled at the 2019 Lumber Liquidators Annual Shareholder Meeting. Our goal in rejecting these proposals is to send a message to the company that excessive pay packages (Proposal 3) will not be tolerated, especially for severe underperformance, and that shareholders will not allow their holdings to be further diluted so that management can receive larger equity base compensation (Proposal 4).
In this article, I would like to compare Lumber Liquidators' director compensation to the companies within its self-selected peer group. In particular, I would like to focus on the pay package of the company Chair, Nancy M. Taylor.
READ FULL ARTICLE HERE

